The ARM discount fell from a full point to almost nothing in two weeks
On Oct 30 a 5/1 ARM priced a point under a 30-year fixed and drew 11.4% of applications. By Nov 13 Zillow had the ARM higher. Here's what the reset costs.
By the numbers
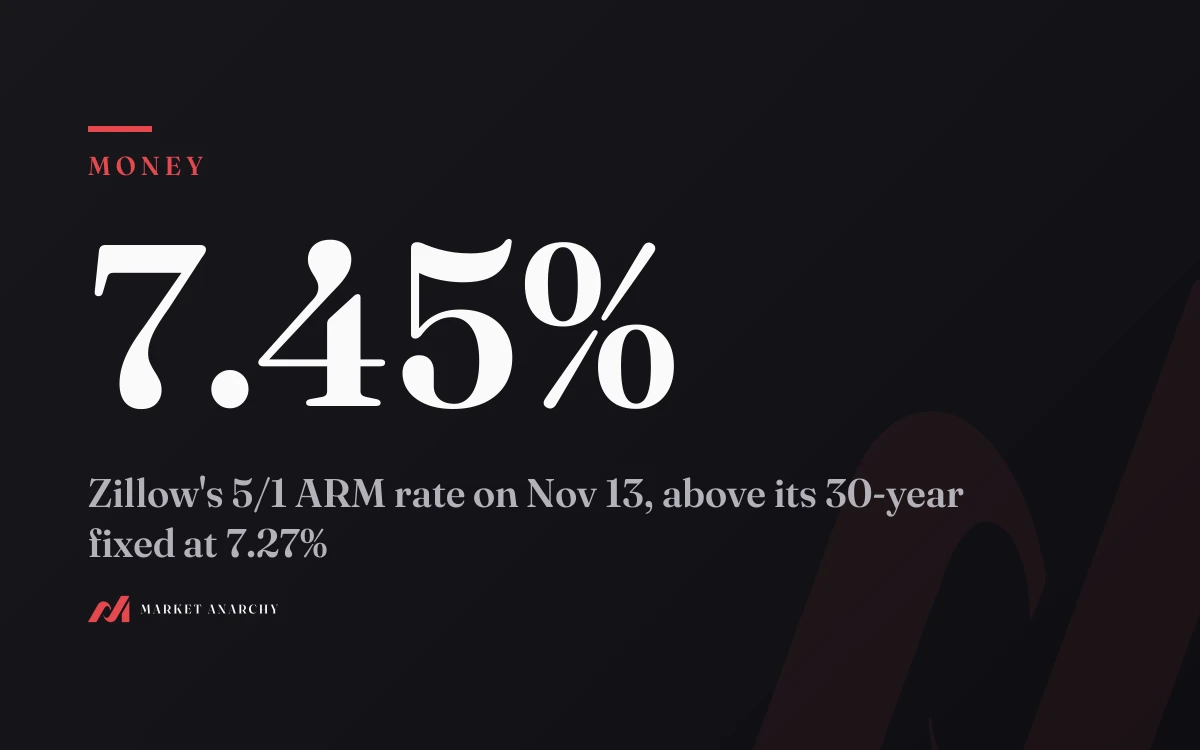
7.45%Zillow's 5/1 ARM rate on Nov 13, above its 30-year fixed at 7.27%
1.01 ptshow far the 5/1 ARM sat under the 30-year fixed in MBA's Oct 30 week
11.4%ARM share of mortgage applications that week, the highest since September 2025
3.92%30-day average SOFR on Nov 13, the index new conforming ARMs reset on
Two weeks ago an adjustable-rate mortgage was the cheap way into a house. In the Mortgage Bankers Association's survey for the week ending October 30, the average 5/1 ARM carried 6.29% against 7.30% for a 30-year fixed, a gap of a full point, and ARMs took 11.4% of all applications, their highest share since September 2025 (MPA, reporting the MBA survey, Nov 4, 2026).
By Friday, November 13, that gap had nearly closed. Zillow's lender data had the 5/1 ARM at 7.45% and the 30-year fixed at 7.27%, so the adjustable loan cost more (Yahoo Finance, Zillow data as of Nov 13, 2026). A review of lender rate sheets the same day put the 7/6 SOFR ARM at 7.05%, 37 basis points under its 30-year reading of 7.42% (Nadlan Capital Group, Nov 13, 2026).
So here's the answer for anyone choosing a loan this month. On a $400,000 mortgage, the ARM's head start has shrunk from about $269 a month to somewhere between $100 a month and nothing, depending on whose survey you trust. The reset risk that came with the discount is all still there. And the index those loans reset on is the one the Fed is about to push up.
What moved between October 30 and November 13
The trigger was the October inflation report. Consumer prices rose 0.4% in October and the core index rose 0.3% for a third straight month, the Bureau of Labor Statistics reported on November 10 (BLS, CPI release, Nov 10, 2026). Economists polled by FactSet had expected 0.3% on the headline. After the release, CME's FedWatch tool showed an 85% chance of a quarter-point hike on December 9 and a 15% chance of a half point, which leaves no room for a pause (CBS News, Nov 11, 2026).
The Fed's target range sits at 3.75% to 4.00% after its September increase. On November 13 Bank of America moved its call to three straight quarter-point hikes, in December, January and March, for a top of 4.50% to 4.75% (24/7 Wall St., Nov 13, 2026). The 10-year Treasury yield closed the week near 5.10% (Nadlan, above).
Every mortgage rate went up. Zillow's 30-year fixed rose 41 basis points in a week. Its 5/1 ARM rose 72 (Yahoo Finance, above).
Why the adjustable loan took the bigger hit is our read; no lender has said so. An ARM's first five or seven years are priced off where short and medium rates are expected to go over that stretch. When traders add three hikes in four months, the near end of the yield curve moves more than the long end that drives the 30-year. That's the end the ARM sits on.
The surveys disagree, and the gap is the whole story
| Survey | Date | ARM rate | 30-year fixed | ARM discount |
|---|---|---|---|---|
| MBA, 5/1 ARM | week ending Oct 30 | 6.29% | 7.30% | 1.01 pts |
| MBA, 5/1 ARM | week ending Nov 6 | 6.28% | 7.21% | 0.93 pts |
| Lender rate sheets, 7/6 SOFR ARM | Nov 13 | 7.05% | 7.42% | 0.37 pts |
| Zillow, 5/1 ARM | Nov 13 | 7.45% | 7.27% | -0.18 pts |
Sources: MPA and RISMedia for Oct 30, Mortgage News Daily for Nov 6, Nadlan and Yahoo Finance for Nov 13.
Three cautions on reading that table.
First, the surveys measure different loans. MBA's ARM rate came with 1.00 point paid at closing on October 30 and 1.14 points on November 6, so it's cheaper on the rate partly because the borrower paid upfront. The rate-sheet survey tracks a 7/6 ARM, which stays fixed two years longer than a 5/1.
Second, the official weekly numbers lag the jump. Freddie Mac's survey released on November 12 had the 30-year fixed at 7.11%, its fourth weekly decline (Freddie Mac via GlobeNewswire, Nov 12, 2026). Mortgage News Daily, writing up MBA's November 6 week, called its own report "a bit of a retrospective" because rates had risen sharply since. MBA's survey for the week ending November 13, due Wednesday, November 18, is the first official read that covers the move.
Third, one week is one week. If November's data cools and the market prices out a hike, the ARM discount can reopen as fast as it closed.
The payment math on a $400,000 loan
These are our calculations: principal and interest on a 30-year schedule, no taxes or insurance, using the rates in the table.
- October 30, MBA: the fixed loan cost $2,742 a month and the 5/1 ARM $2,473. The ARM saved $269 a month, about $16,100 over its five fixed years.
- November 13, rate sheets: the fixed loan cost $2,775 and the 7/6 ARM $2,675. The ARM saved about $100 a month, roughly $8,400 over seven fixed years.
- November 13, Zillow: the fixed loan cost $2,734 and the 5/1 ARM $2,783. The ARM cost $49 a month more from the first payment.
A borrower who took an ARM in late October bought a discount worth about $16,000. A borrower comparing quotes today is being offered a much smaller one, or none, for the same reset risk.
What the reset can cost
Most new conforming ARMs follow the Fannie Mae and Freddie Mac SOFR terms. The rate resets every six months after the fixed period, to the 30-day average SOFR plus a margin of 2.75% to 3.00%. A 5-year ARM can rise at most 2 points at the first reset, 1 point at each later one and 5 points over the life of the loan. Seven- and 10-year ARMs can rise 5 points at the first reset (Pennymac, conforming SOFR ARM overview).
The 30-day average SOFR was 3.92% on November 13 (New York Fed, SOFR averages). Add the margin and a loan resetting today would land at 6.67% to 6.92%. Under Bank of America's path, and assuming SOFR rises with the 0.75 points of hikes (our assumption), the same reset would land near 7.42% to 7.67%. That's about where Zillow's 5/1 ARM starts. Nobody can tell you where SOFR will sit in 2031, which is when a loan taken this month first resets.
The cap sets the worst case. A 5/1 ARM at 7.45% can jump to 9.45% at the first reset. After five years of payments the balance on a $400,000 loan is about $378,300, and at 9.45% over the remaining 25 years the payment becomes about $3,292. That's $558 a month above today's 30-year fixed at 7.27%, again our arithmetic.
There's one more catch for buyers using an ARM to qualify for a bigger loan. Fannie Mae underwrites a 5-year ARM at the higher of the note rate plus the first-change cap or the fully indexed rate (Fannie Mae Selling Guide, B3-6-04). A 5/1 at 7.45% is judged as if it cost 9.45%. The lower starting payment doesn't stretch the approval. Seven- and 10-year ARMs are generally qualified at the note rate, which is part of why the 7/6 quote in the table is the one still worth asking about.
Who this is for, and what to watch
This is for a buyer choosing a loan type in the next few weeks. The useful move is a same-day quote for both loans with the same points, because the published averages disagree by more than half a point on the gap alone. At a 0.37-point discount, a 7/6 ARM buys about $100 a month for seven years and leaves the eighth year open. At Zillow's numbers, the ARM costs more from day one.
It doesn't apply to anyone already holding an ARM: their start rate is fixed until the first reset. And it doesn't apply to a borrower who plans to sell or refinance well inside the fixed period, for whom the reset never arrives.
For the bond side of this move, our guide to what mortgage-backed securities yield in 2026 is kept current, and the CPI timing we covered on November 9 explains why November's prices land after the Fed decides. Two dates decide whether the discount comes back: MBA's survey on November 18 and the Fed's decision on December 9.
Sources
- MPA: Mortgage applications slip as ARM share hits 14-month high, Nov 4, 2026
- RISMedia: Share of ARMs hits highest level since September 2025, Nov 4, 2026
- Mortgage News Daily: MBA applications, week ending Nov 6, published Nov 13, 2026
- Yahoo Finance: Zillow mortgage rates, Nov 15, 2026
- Nadlan Capital Group: Mortgage rates, Nov 13, 2026
- Freddie Mac via GlobeNewswire: Mortgage rates decline for fourth consecutive week to 7.11%, Nov 12, 2026
- BLS: Consumer Price Index, October 2026, released Nov 10, 2026
- CBS News: October CPI and Fed hike odds, Nov 11, 2026
- 24/7 Wall St.: Bank of America changes its Fed call to three hikes, Nov 13, 2026
- New York Fed: SOFR averages and index
- Pennymac: Conforming SOFR ARM overview
- Fannie Mae Selling Guide B3-6-04: Qualifying payment requirements
This is not financial advice.
More from Money
Can you sell your Anthropic IPO shares? Each broker's rule, in days
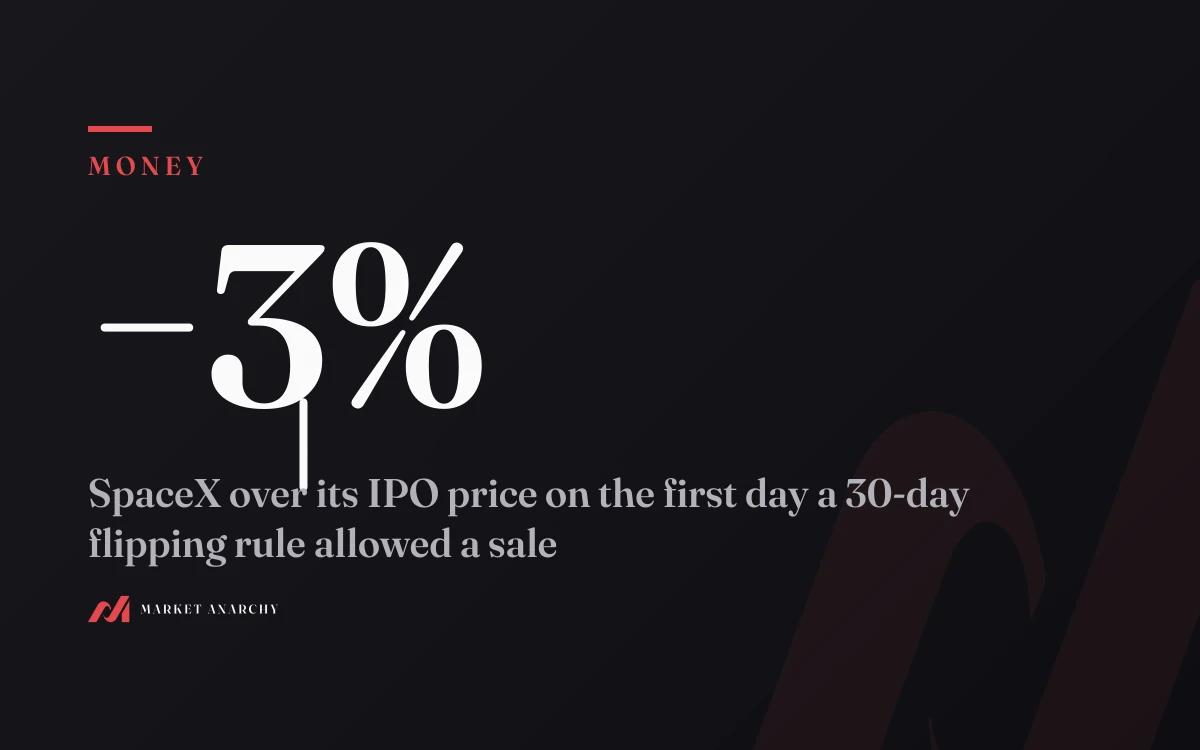
Fidelity lets ANT buyers sell penalty-free December 4, Robinhood and SoFi after 30 days, Schwab today. SpaceX's 30-day wait shrank a 57% gain to 3%.